
What is a key person insurance policy?
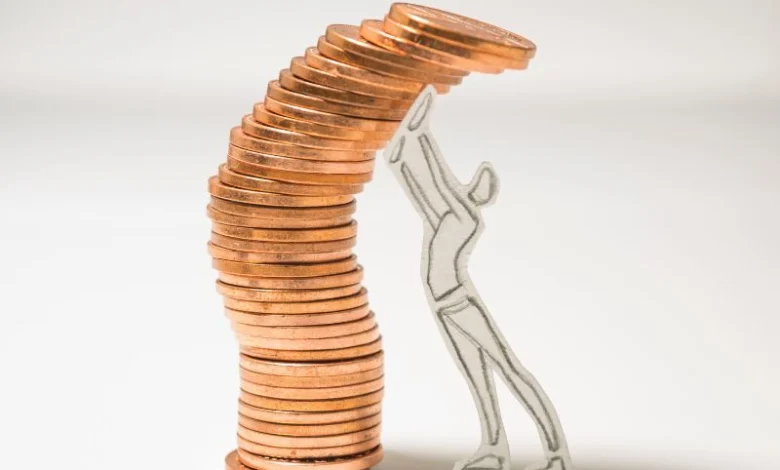
What is a key person insurance policy?
Understanding Credit Scores
Every American adult has a credit score, a crucial number that can impact everything from buying a car to renting an apartment or qualifying for a mortgage. If you’ve ever wondered what a credit score really means, how it’s calculated, and why it’s so important, you’re in the right place. This article will walk you through a detailed explanation of credit scores, how they influence your financial life, and tips to improve yours.
What Is a Credit Score?
A credit score is a three-digit number that represents your creditworthiness based on your financial behavior. Think of it as a snapshot snapshot of how responsible you are with borrowing money and paying it back on time. Lenders, landlords, and even some employers might use this number to assess your reliability.
In the United States, credit scores generally range from 300 to 850. The higher the score, the better you look to lenders and other decision-makers.
Who Creates Your Credit Score?
Your credit score is calculated by credit reporting agencies (also known as credit bureaus). The three main bureaus in the U.S. are:
- Equifax
- Experian
- TransUnion
Each bureau collects data about your financial habits, including loans, credit cards, payment history, and more. They use this data to generate your credit score, often through models like the FICO Score or VantageScore.
Why Is Your Credit Score Important?
Your credit score affects many aspects of your financial life. Here are some areas influenced by your credit score:
- Loan approvals: Lenders check your score to decide if they want to lend you money.
- Interest rates: Higher scores often mean lower interest rates on loans and credit cards.
- Housing applications: Landlords may check your score before renting to you.
- Utilities and cell phone plans: Some companies require a good credit score or a deposit.
- Employment opportunities: Certain employers check credit scores during the hiring process.
How Is a Credit Score Calculated?
Credit scores are calculated based on several key factors. While different models weigh these elements slightly differently, here’s a general breakdown of what makes up your credit score:
- Payment History (35%): This is the single most important factor. It reflects whether you’ve paid your bills on time.
- Amounts Owed (30%): Also called credit utilization, this considers how much of your available credit you’re using.
- Length of Credit History (15%): The longer your credit accounts have been open and in good standing, the better.
- New Credit (10%): Opening several new accounts quickly can lower your score.
- Credit Mix (10%): Having a variety of credit types—such as installment loans, credit cards, and mortgages—can be beneficial.
Key Terms Related to Credit Scores
To fully grasp how credit scores work, it’s helpful to be familiar with the following terms:
- Credit Report: A detailed record of your credit history, including loans, credit cards, account balances, and payment activity.
- Credit Utilization: The ratio of your current credit card balances to your available credit limits.
- Hard Inquiry: A credit check triggered when you apply for credit, which can slightly lower your score.
- Soft Inquiry: A credit check that doesn’t affect your score, such as when you check your own score.
- Installment Loan: Loans like car loans or mortgages where you make fixed payments over time.
- Revolving Credit: Credit like credit cards where you can borrow repeatedly up to a limit.
- Charge-Off: When a creditor writes off your debt as a loss after prolonged nonpayment.
How to Check Your Credit Score
Checking your credit score regularly is a smart habit. It helps you understand your financial standing and detect errors or potential fraud early.
You can check your credit score for free through:
- AnnualCreditReport.com: The only federally authorized site to get free credit reports from Equifax, Experian, and TransUnion once a year.
- Credit card companies: Many issuers provide free FICO or VantageScores to their customers monthly.
- Personal finance apps: Tools like Credit Karma and Mint offer free access to your credit score and reports.
Remember: Checking your own score is a soft inquiry and will not hurt your credit.
Tips to Improve Your Credit Score
If your credit score isn’t where you’d like it to be, don’t worry. There are proven strategies to boost it over time:
- Pay bills on time: Payment history is essential; set reminders or automate payments to avoid late payments.
- Keep credit card balances low: Aim to use less than 30% of your available credit limits.
- Avoid opening too many new accounts quickly: Each new application can cause a small, temporary score drop.
- Keep old credit accounts open: Length of credit history positively impacts your score.
- Regularly check your credit reports: Dispute any errors or inaccuracies immediately.
Common Misconceptions About Credit Scores
There are plenty of myths about credit scores that can confuse consumers. Let’s clear up some of the most common ones:
- Checking your credit lowers your score: Soft inquiries, like checking your own score, do not affect your credit.
- A higher income means a higher credit score: Your income does not factor into the credit scoring models.
- Closing old credit cards will improve your score: Actually, closing old accounts can shorten your credit history and increase your utilization ratio, potentially lowering your score.
- Paying off a debt removes it from your report immediately: Paid debts can still appear for seven years, though they no longer negatively affect your score.
How Credit Scores Affect Loans and Interest Rates
When you apply for a loan—be it for a car, home, or personal use—lenders rely heavily on your credit score. A higher score typically qualifies you for:
- Lower interest rates: Borrowing money becomes cheaper when your credit risk is lower.
- Higher loan amounts: You might be able to borrow more if lenders trust you to pay back.
- Better loan terms: Longer repayment periods or waived fees.
In contrast, a low credit score can result in higher costs or even loan denials. That’s why maintaining a good credit score is a key part of financial health.
How Long Does Bad Credit Impact Your Score?
Negative items on your credit report don’t stick around forever, but they can affect your score for several years:
- Late payments: Stay on your report for up to 7 years.
- Charge-offs: Also remain for up to 7 years.
- Bankruptcies: Can stay on your report for 7 to 10 years, depending on the type.
- Collections: Usually stay for 7 years plus 180 days from the date of the first missed payment.
Improving your score requires patience but focusing on positive behaviors can gradually repair your credit history.
Credit Scores and Identity Theft
Identity theft can wreak havoc on your credit score. Criminals may fraudulently open new accounts or rack up charges in your name, leading to missed payments and debt you never knew existed.
To protect yourself:
- Monitor your credit reports frequently.
- Set up alerts on your accounts.
- Freeze your credit if you suspect fraud.
- Report suspicious activity immediately.
Conclusion
Your credit score is a powerful number that influences many financial decisions and opportunities. By understanding how it’s calculated, why it matters, and how you can improve it, you take control of your financial future. Remember: consistent, responsible financial behavior is the key to maintaining a strong credit score that opens doors, saves you money, and provides peace of mind.

Related Articles
Our HOME in English: Smart Finance: Learn, Invest, and Grow

Our Categories:
- 💳 Credit Cards: Comparisons, reviews, and tips to choose the best card for your profile — cashback, travel rewards, no annual fee, and more.
- 🏦 Digital Banks: Practical guides and evaluations of digital bank accounts, fees, benefits, and services.
- 📈 Investments: Beginner guides, fixed income and variable income options, real estate investment trusts (REITs), and more.
- 🧮 Financial Education: Learn to manage your budget, build an emergency fund, and get out of debt.
- 🚗 Loans and Financing: Explanations about mortgage, auto, and student loans, with smart money-saving tips.
- 🛡️ Insurance: Information about the most important types of insurance to protect your family and assets.
- 📊 Taxes and Income: Guidance on tax filing, investment taxation, and fiscal responsibilities.
- 🏖️ Retirement Planning: Tips to plan your retirement with private retirement plans, Social Security benefits, and passive income strategies.

What is a Key Person Insurance Policy?
Running a business comes with many risks, including the potential loss of a crucial team member whose skills, knowledge, or leadership directly impact company success. A key person insurance policy offers financial protection to businesses by providing a payout if an essential employee passes away or becomes incapacitated. This kind of insurance helps companies cover loss of revenue, recruitment costs, and stabilize operations while they adjust to the change. Understanding the benefits and mechanics of key person insurance is vital for American business owners looking to safeguard their investments and future growth.
Conclusion
In summary, a key person insurance policy is a smart financial tool for businesses that depend heavily on certain individuals. It serves as a safety net, ensuring that the organization can endure unexpected setbacks caused by the loss of a top performer or leader. This insurance not only replaces lost revenue but also helps cover recruitment and training expenses, boosting your business’s resilience. For American business owners, investing in key person insurance means peace of mind and a stronger chance to maintain continuity. If your team includes irreplaceable members contributing directly to your company’s success, securing a key person policy could be one of your wisest decisions.
Frequently Asked Questions
What exactly is key person insurance?
It’s a life insurance policy purchased by a business to protect against financial loss if a vital employee dies or becomes disabled.
Who qualifies as a key person in a business?
A key person is someone whose skills, knowledge, or leadership are essential to business success, like founders, executives, or top salespeople.
How does key person insurance work?
The business pays premiums and receives a payout if the insured key person dies or becomes incapacitated, helping cover financial gaps.
Can a small business benefit from key person insurance?
Yes, small businesses especially benefit because the loss of one key individual can have a bigger impact on their operations.
Is key person insurance the same as business insurance?
No, key person insurance specifically protects against the loss of essential employees, whereas business insurance covers liabilities and assets.
Who pays for the key person insurance premiums?
The business usually pays the premiums and is the beneficiary of the policy’s payout.
Can key person insurance cover disability?
Some policies include disability coverage, but you should confirm this when selecting your plan.
How is the value of key person insurance determined?
It’s based on the financial impact the key person’s absence would have on the company, including lost revenue and recruitment costs.
Is key person insurance tax deductible?
In many cases, premiums aren’t tax deductible, but consult a tax professional for advice specific to your situation.
Can the policy be used for multiple key persons?
Typically, policies cover one individual, but businesses can buy multiple policies for different key employees.
How long does it take to get coverage?
Approval and coverage usually start within a few weeks, depending on underwriting requirements and medical exams.
Does key person insurance cover natural death and accidents?
Yes, most policies cover death due to natural causes, illness, or accidents.
Can the key person insurance policy be transferred?
Policies are generally owned by the business and aren’t transferable to individuals.
What happens to the business if the key person dies but there’s no insurance?
The business may face financial hardship, loss of clients, or strained operations without this safety net.
How can key person insurance help attract investors?
It shows that the business plans for contingencies, offering reassurance about financial stability and risk management.






